Guide · Customs
Proforma Invoice for Customs Clearance
“Can I clear my goods with a proforma invoice?” is one of the most common questions in international trade, and the honest answer is: usually not for a definitive commercial import, but very often for everything that surrounds it. Understanding exactly where customs accepts a proforma — and where it will refuse one — saves days of storage charges.
Updated 17 October 2026 · 4 min read
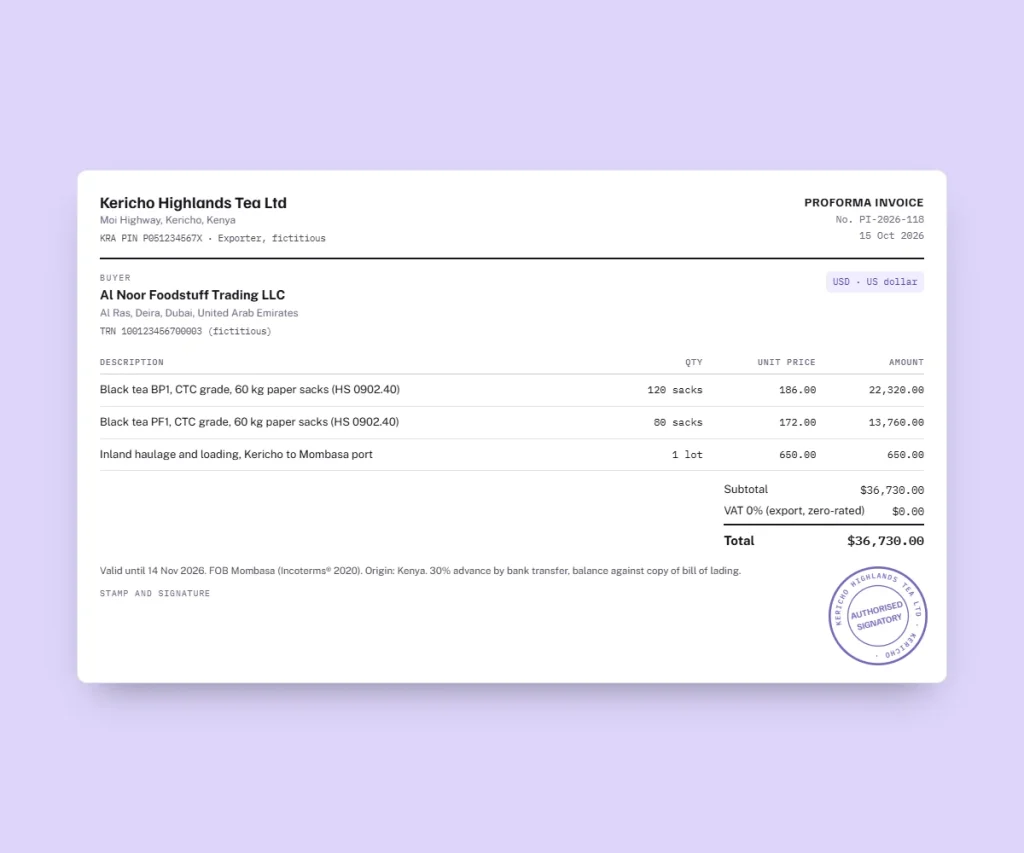
From the guide to the document
Your proforma with these details, ready as a PDF.
Why customs prefers the commercial invoice
Duty is calculated on the customs value, and under the WTO Valuation Agreement the primary method is the transaction value: the price actually paid or payable for the goods when sold for export to the country of importation. A proforma states a price that may be paid. A commercial invoice states a price that has been agreed for goods that have actually shipped. Only the second is evidence of a transaction, which is why customs administrations build their entry procedures around it.
There is a second reason. The commercial invoice is an accounting document in both companies’ books. If a declared value is later challenged, an auditor can trace it to a ledger entry and a payment. A proforma leaves no such trail.
Where a proforma invoice is accepted
| Situation | Why a proforma works | Typical wording |
|---|---|---|
| Import licence or permit applications | The licence is applied for before the goods exist; the authority needs description, value, HS codes and origin | Standard proforma, validity long enough to cover the approval time |
| Foreign-exchange approval and bank registration | Exchange-control regimes register the transaction before funds leave the country | Signed and stamped; supplier bank details; often a specific validity minimum |
| Opening a letter of credit | The credit is written from the proforma | Full trade terms; see the L/C guide |
| Samples of no commercial value | No sale takes place, so no commercial invoice exists | “Sample — no commercial value. Value stated for customs purposes only.” |
| Temporary admission (exhibitions, demonstration equipment, professional gear) | Goods enter and leave again; value is needed only to secure the guarantee | “Temporary importation — goods to be re-exported. Value for customs purposes only.” An ATA Carnet is often the cleaner route |
| Goods sent for repair, and their return | No change of ownership; duty may apply only to the repair cost | Reference the original export declaration and state the repair value separately |
| Warranty replacements sent free of charge | No payment is made | “Free of charge replacement under warranty. Value for customs purposes only.” |
| Gifts and low-value personal shipments | Courier systems accept a proforma below de minimis thresholds | Realistic value, clear description, HS code |
| Advance rulings and duty estimates | The broker prices the entry before the goods leave | Full specification and HS codes |
Never write “no value”
A shipment always has a customs value, even when nobody pays for it. Declaring zero is the fastest way to have a consignment held while customs assigns its own value — usually a conservative one, with duty to match. For free-of-charge goods, state a realistic value based on cost or on the price of identical goods, and add the phrase “value for customs purposes only, goods supplied free of charge”. That is a lawful declaration; “no commercial value, USD 0” is not.
What customs looks at on the document
- Description of goods. Specific enough to classify. “Spare parts” invites the officer to pick a heading for you.
- HS code per line, and whether it is plausible for the description given. See the HS code guide.
- Country of origin, which drives preferential duty, anti-dumping measures and quota treatment.
- Incoterms rule and named place, because they determine whether freight and insurance are already inside the price or must be added to reach the customs value.
- Freight and insurance shown separately where the destination values on a CIF basis, or where deductions are allowed on a delivered price.
- Currency and exchange rate. The declaration uses the official rate for the day; a document without a stated currency cannot be processed.
- Relationship between buyer and seller. Related-party transactions can trigger a valuation review.
- Additions to the price such as royalties, licence fees, assists, tooling and commissions, which may be dutiable even when invoiced separately.
Corridor examples
The role of the proforma varies sharply between markets. These are patterns exporters meet frequently; always confirm the current rule, because trade regulations change without much warning.
| Destination | Where the proforma is used | Notes for the exporter |
|---|---|---|
| European Union | Rarely required by customs; used commercially and for prepayments | Importer needs an EORI number; the commercial invoice supports the declaration and the VAT position |
| United States | Accepted for samples and some informal entries | Formal entry above the low-value threshold relies on the commercial invoice; ocean shipments need an advance security filing |
| United Kingdom | Similar to the EU | Preference claims require a statement on origin or supplier declarations |
| Nigeria | Central to the process — a supplier proforma opens the Form M before shipment | Product certification and pre-shipment conformity assessment usually apply |
| Kenya | Used to open the import declaration form | Pre-export verification of conformity for regulated products |
| Algeria and several exchange-control markets | Required for bank domiciliation before funds transfer | Validity, signature and stamp are checked closely; expect a minimum validity requirement |
| Saudi Arabia and the Gulf | Used for conformity registration and for opening credits | Product conformity certificates are obtained before shipment; some documents still require legalisation |
| India | Used for advance remittance and licence applications | Importer needs an Importer-Exporter Code; the bill of entry is filed on the commercial invoice |
| Egypt | Used commercially, alongside advance cargo information | Shipping documents must quote the advance clearance reference obtained by the importer |
Making the transition to the commercial invoice painless
- Quote the proforma number on the commercial invoice, so the licence file and the entry can be tied together.
- Keep line items in the same order, with the same descriptions, HS codes and origins.
- Do not change the Incoterms rule between the two documents; if the buyer wants a change, reissue the proforma and let them amend their licence or credit.
- If quantities changed, check the tolerance the licence or the credit allows before shipping — an overshipment can be as damaging as a short shipment.
- Send scanned copies of the full set to the buyer as soon as the vessel sails, so their broker can pre-lodge the entry.
See proforma invoice vs commercial invoice for the full comparison, and the export documents checklist for the rest of the file. You can turn the accepted proforma into the invoice in one click, so the lines are copied rather than retyped.
Customs rules differ by country and change frequently. This page is general information for exporters and importers, not customs advice. Verify requirements with the destination customs authority or a licensed customs broker before shipping.
Read next
Related guides
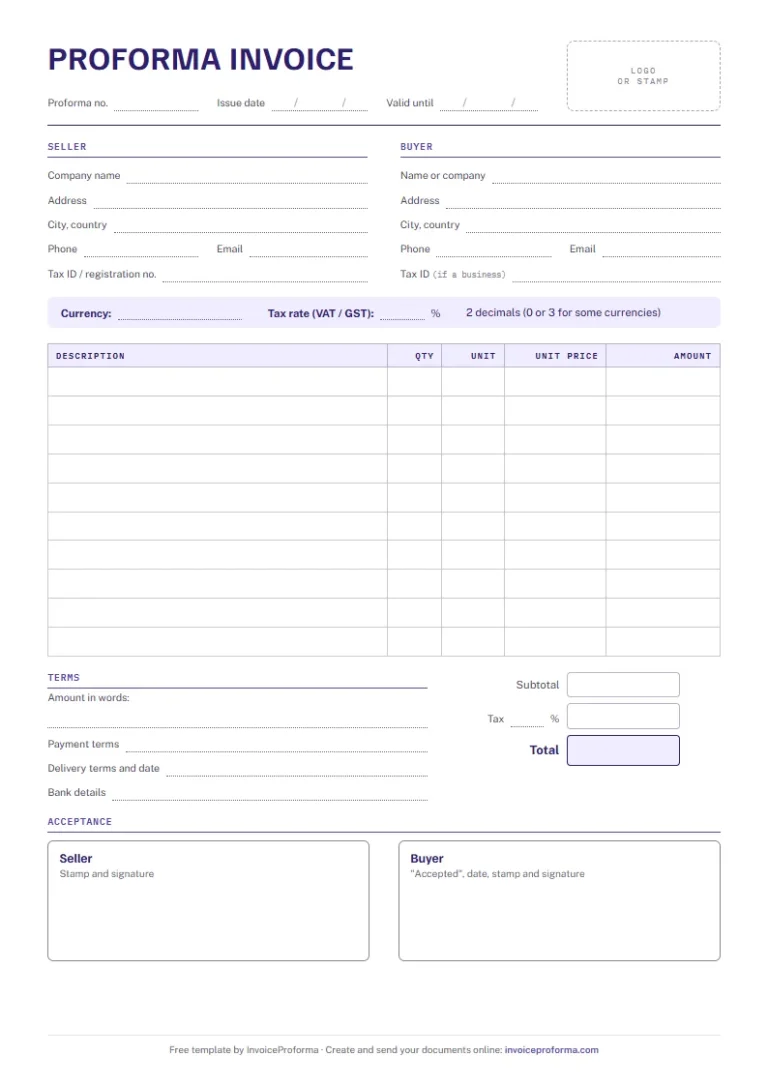
Which document does customs need, and which does the bank? A field-by-field comparison of proforma and commercial invoices, and errors that delay shipments.
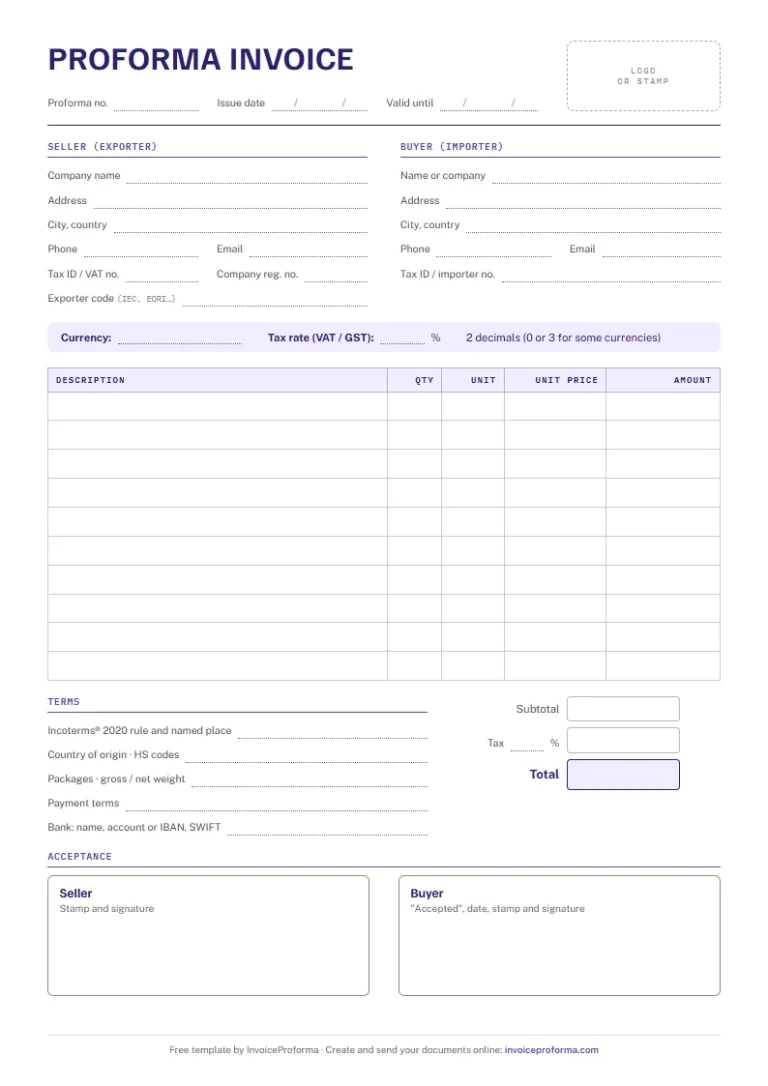
Commercial invoice, packing list, bill of lading, certificate of origin and destination-specific papers, with the consistency rules that prevent port delays.
How Harmonized System codes are built, what the six digits mean, the rules that settle classification disputes, and a practical method for finding your code.
Six documents, one app
From the quote to the receipt
One customer file, one product list and your own layout serve all six documents. An accepted quote or proforma becomes an invoice without retyping.
1. The price
Quote
QUO-2026-0012
Your price for the job, with a validity date and space for the buyer to accept it.
2. The firm offer
Proforma invoice
PI-2026-042
What your buyer’s bank, their forwarder or their purchasing team asks for before the order.
3. The order
Purchase order
PO-2026-0007
What is ordered, how many and for which delivery date, signed by the buyer.
4. The delivery
Delivery note
DN-2026-0007
It travels with the goods; the consignee signs it and writes down any reservation.
5. The sale
Invoice
INV-2026-0031
The accepted proforma or quote becomes the invoice, with the same lines and currency.
6. The payment
Payment receipt
REC-2026-0019
Proof of a payment, linked to its invoice, with the method and the balance still due.
3 free documents to try it, no card required.
Your next proforma invoice, already in your colours
Three free documents, no card required. Your tax IDs, bank details and payment terms are typed once, then printed on every PDF.